Need to sell your current home before you can buy your next one? A contingent offer can still win — but only if it's built right.We walk through what makes yours the one a Willamette Valley
Dated: July 29 2024
Views: 145
As someone who’s thinking about buying or selling a home, you’re probably paying close attention to mortgage rates – and wondering what's ahead.
One thing that can affect mortgage rates is the Federal Funds Rate, which influences how much it costs banks to borrow money from each other. While the Federal Reserve (the Fed) doesn’t directly control mortgage rates, they do control the Federal Funds Rate.
The relationship between the two is why people have been watching closely to see when the Fed might lower the Federal Funds Rate. Whenever they do, that’ll put downward pressure on mortgage rates. The Fed meets this week, and three of the most important metrics they’ll look at as they make their decision are:
Here’s the latest data on all three.
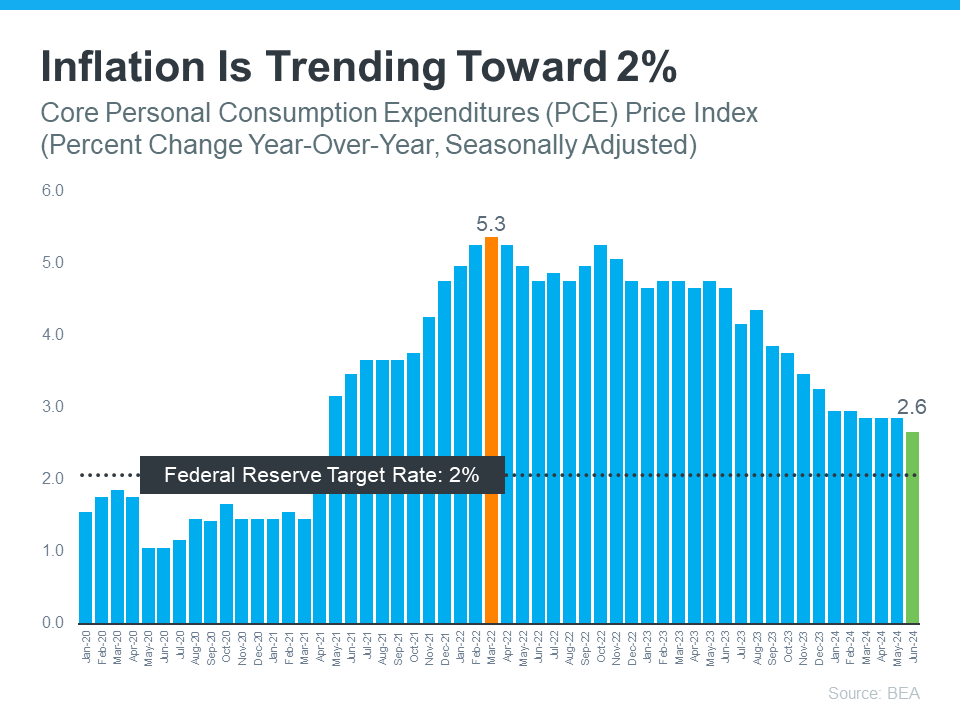
You’ve probably heard a lot about inflation over the past year or two – and you’ve likely felt it whenever you’ve gone to buy just about anything. That’s because high inflation means prices have been going up quickly.
The Fed has stated its goal is to get the rate of inflation back down to 2%. Right now, it’s still higher than that, but moving in the right direction (see graph below):
 2. How Many Jobs the Economy Is Adding
The Fed is also watching how many new jobs are created each month. They want to see job growth slow down consistently before taking any action on the Federal Funds Rate. If fewer jobs are created, it means the economy is still strong but cooling a bit – which is their goal. That appears to be exactly what’s happening now. Inman says:
“. . . the Bureau of Labor Statistics reported that employers added fewer jobs in April and May than previously thought and that hiring by private companies was sluggish in June.”
So, while employers are still adding jobs, they’re not adding as many as before. That’s an indicator the economy is slowing down after being overheated for quite some time. This is an encouraging trend for the Fed to see.
The unemployment rate is the percentage of people who want to work but can’t find jobs. So, a low rate means a lot of Americans are employed. That’s a good thing for many people.
But it can also lead to higher inflation because more people working means more spending – which drives up prices. Right now, the unemployment rate is low, but it’s been rising slowly over the past few months (see graph below):
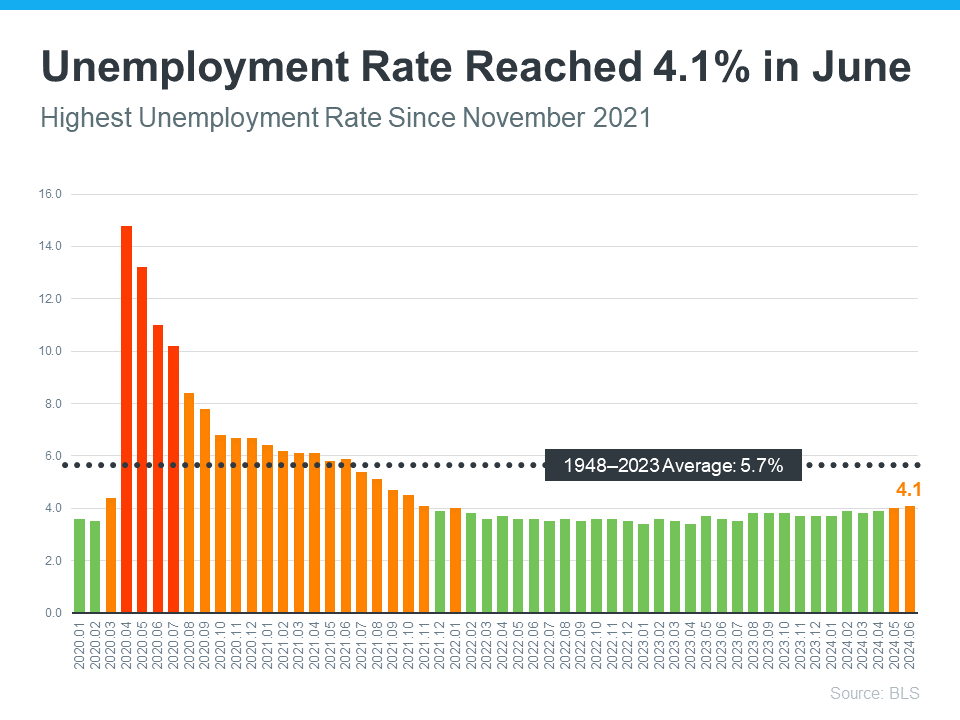 It may seem harsh, but a consistently rising unemployment rate is something the Fed needs to see before deciding to cut the Federal Funds Rate. That’s because a higher unemployment rate would mean reduced spending, and that would help get inflation back under control.
While mortgage rates are going to continue to be volatile in the days and months ahead, these are signs the economy is headed in the direction the Fed wants to see. But even with that, it’s unlikely they'll cut the Federal Funds Rate when they meet next week. Jerome Powell, Chair of the Federal Reserve, recently said:
“We want to be more confident that inflation is moving sustainably down toward 2% before we start the process of reducing or loosening policy.”
Basically, we’re seeing the first signs now, but they need more data and more time to feel confident that this is a consistent trend. Assuming that direction continues, according to the CME FedWatch Tool, experts say there’s a projected 96.1% chance the Fed will lower the Federal Funds Rate at their September meeting.
Remember, the Fed doesn’t directly set mortgage rates. It’s just that whenever they decide to cut the Federal Funds Rate, mortgage rates should respond.
Of course, the timing of when the Fed takes action could change because of new economic reports, world events, and other factors. That’s why it's usually not a good idea to try to time the market.
We're hopeful that recent economic data may signal that hope is on the horizon for mortgage rates. Connect with us so we can help keep you up to date on the latest trends and what they mean for you.
Welcome — we’re glad you’re here.We’re Ruth and Frank Howard, known locally as Your Howard Team, and we help homeowners across the Willamette Valley make smart, confident real ....
Need to sell your current home before you can buy your next one? A contingent offer can still win — but only if it's built right.We walk through what makes yours the one a Willamette Valley
A contingent offer on your home isn't automatically a risk — but it does come with real tradeoffs worth understanding before you sign.Here's how Oregon's contingency structure protects,
Buying a home where the seller is signing under power of attorney? The legal ground rules haven't changed — but where you focus your due diligence should.Here's what buyers in the Willamette
Selling Mom or Dad's house under power of attorney? Here's what actually changes in the transaction — from disclosure requirements to closing — and what doesn't.Read our full blog
 All information provided is deemed reliable but is not guaranteed and should be independently verified. IDX information is provided exclusively for consumers' personal, non-commercial use, that it may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing, and that the data is deemed reliable but is not guaranteed accurate by RMLSTM.
The content relating to real estate for sale on this web site comes in part from the IDX program of the RMLSTM of Portland, Oregon. Real estate listings held by brokerage firms other than Equity Oregon Real Estate are marked with the RMLSTM logo, and detailed information about these properties includes the names of the listing brokers. Listing content is copyright © 2026 RMLSTM, Portland, Oregon.
This content last updated on September 21, 2026 1:28 PM UTC at 4 AM. Some properties which appear for sale on this web site may subsequently have sold or may no longer be available.
